06 Mauritius & global context

2,040 square
kilometres, four
economies deep.

No career happens in a vacuum. This is the economy in which a Mauritian group leader spent five decades allocating capital — documented, quantified and set against the wider Indian Ocean and African context.

i The position

An island that decided
to be a junction.

Mauritius is a volcanic island in the south-west Indian Ocean, roughly 2,000 kilometres off the East African coast, with a population of about 1.27 million. It has no oil, no significant minerals, no hinterland and no domestic market of any consequence. In the 1960s, a widely cited economic assessment of the territory concluded that its prospects were poor: a densely populated, sugar-dependent island facing rapid population growth.

What Mauritius built instead of resources was position. It is a member of the African Union, the Southern African Development Community, COMESA, the Indian Ocean Rim Association, the Commonwealth and the Organisation internationale de la Francophonie. Its legal system is a hybrid of French civil law and English common law. Its workforce operates in English, French and Creole, with significant Hindi, Bhojpuri, Urdu, Tamil and Chinese-dialect communities linking it culturally and commercially to South Asia and East Asia.

That combination — African membership, Asian ties, European legal familiarity, an English-language business environment and a functioning stock exchange — is what allows a company headquartered in Port Louis to be genuinely international at modest scale. It is also precisely the combination on which the Mauritian financial-services sector was built.

The independence of that model has been tested. It required, and still requires, political stability, contract enforceability and regulatory credibility, none of which are guaranteed by geography.
Mauritius: key indicators

Population

Approx. 1.27 million (2025)

GDP, nominal

Approx. USD 16.4 billion (2024)

GDP per capita

Approx. USD 12,973 (2024, nominal)

Growth

4.7% in 2024; estimated 3.2% in 2025

Classification

Upper-middle income (World Bank). Briefly classified high-income in July 2020, reverting in 2021.

Unemployment

5.8% at end-December 2024, from 6.1% a year earlier

Financial services

Estimated 13.3% of GDP (2024)

ii Four transitions

The country rebuilt
its economy four times
in sixty years.

Each transition arrived roughly when the previous engine began to lose power. A career spanning 1977 to 2025 sits across three of the four.

Phase one Sugar

Monoculture and its preferences

For most of the twentieth century the Mauritian economy was sugar. Cane defined land use, employment, export earnings and the corporate landscape — CIEL among many companies founded on an estate. The industry’s viability rested substantially on guaranteed access to European markets at prices above world levels, an arrangement that would not last.

Phase two Textiles

The export-processing zone

From the 1970s Mauritius used an export-processing-zone framework to attract garment manufacturing, offering duty-free inputs, competitive labour and preferential access to European and American markets. Textiles displaced sugar as the leading source of foreign exchange and absorbed a rapidly growing labour force, particularly women entering formal employment for the first time. This is the environment Arnaud Dalais joined the corporate sector into, and the one that had matured by the time he became Group Chief Executive in 1991.

Phase three Tourism

Selling the island itself

Upmarket tourism developed alongside manufacturing, built on long-haul European traffic and a deliberately positioned high-value, low-volume model. Arrivals now run at roughly 1.4 million a year — more visitors annually than the island has residents. Tourism brought hard currency and construction demand, and it made the economy sensitive to airline capacity, exchange rates and events on other continents.

Phase four Services

Finance, professional services and ICT

From the 1990s Mauritius built a financial-services sector on treaty networks, regulatory credibility and its position between Africa and Asia, adding business-process outsourcing and ICT in the following decade. Financial services alone accounted for an estimated 13.3 per cent of GDP in 2024. This transition ran through the second half of Arnaud Dalais’s executive tenure and is the reason CIEL has a finance cluster at all.

Why this matters to a group leader — Each transition compressed a generation of industrial change into a few years. A conglomerate operating across all four had to fund the next phase from the cash flows of the last, repeatedly, without knowing which phase would prove durable. This is the strategic environment behind every decision described elsewhere on this site.

iii The economy today

Where the numbers
stand now.

16.4 bn Nominal GDP, USD (2024) For a population of about 1.27 million
12,973 GDP per capita, USD (2024) Upper-middle income by World Bank classification
3.2 % Estimated growth, 2025 Following 4.7% in 2024
13.3 % Financial services share of GDP (2024) Estimated

A moderation, not a reversal

Growth of 4.7 per cent in 2024 moderated to an estimated 3.2 per cent in 2025. The World Bank attributes the slowdown principally to the completion of major infrastructure projects and a consequent easing in new investment, rather than to weakness in the productive economy: tourist arrivals held near record levels, and financial services and ICT continued to expand.

Labour-market indicators improved over the same period. Unemployment stood at 5.8 per cent at the end of December 2024, down from 6.1 per cent a year earlier, and reported measures in 2025 pointed to a further decline. Headline inflation, which had reached 7.0 per cent on a twelve-month average basis in 2023, fell to 2.5 per cent by March 2025.

The high-income question

Mauritius was classified as a high-income economy by the World Bank in July 2020, on 2019 data, and reverted to upper-middle income in 2021 following the pandemic’s impact on tourism. That two-year episode is a useful measure of both the achievement and its fragility: the island came within reach of a threshold few African economies approach, and lost it to a single external shock in a single sector.

For a diversified group, this is the argument for diversification stated at national scale. An economy — or a company — that is one shock away from a step change in classification is carrying more concentration risk than its headline numbers suggest.

iv Africa & the Indian Ocean

The neighbourhood,
and the market.

Mauritius sits inside three overlapping economic geographies. The first is the Indian Ocean island grouping — Madagascar, Seychelles, Comoros, Réunion — small economies with shared logistics constraints and a shared exposure to tourism and cyclones. The second is continental Africa, through the African Union, SADC and COMESA, and increasingly through the African Continental Free Trade Area. The third is the Asian axis: India, Bangladesh, the Gulf, and the shipping lanes that connect them to Europe.

CIEL’s reported operating footprint maps onto all three. The Group states a presence across roughly ten markets in Africa and Asia, with operations reported in Mauritius, Madagascar, India, Bangladesh, the Seychelles, Tanzania, Uganda and the United Arab Emirates.

The commercial logic differs by geography. Madagascar and Bangladesh are principally production geographies for textiles. India is both production and market. East Africa represents growth-market exposure. The Gulf is a services and connectivity node. A single group holding all four types of exposure is doing something more deliberate than opportunistic expansion.

See the cluster structure
  • Mauritius
  • Madagascar
  • India
  • Bangladesh
  • Seychelles
  • Tanzania
  • Uganda
  • U.A.E.
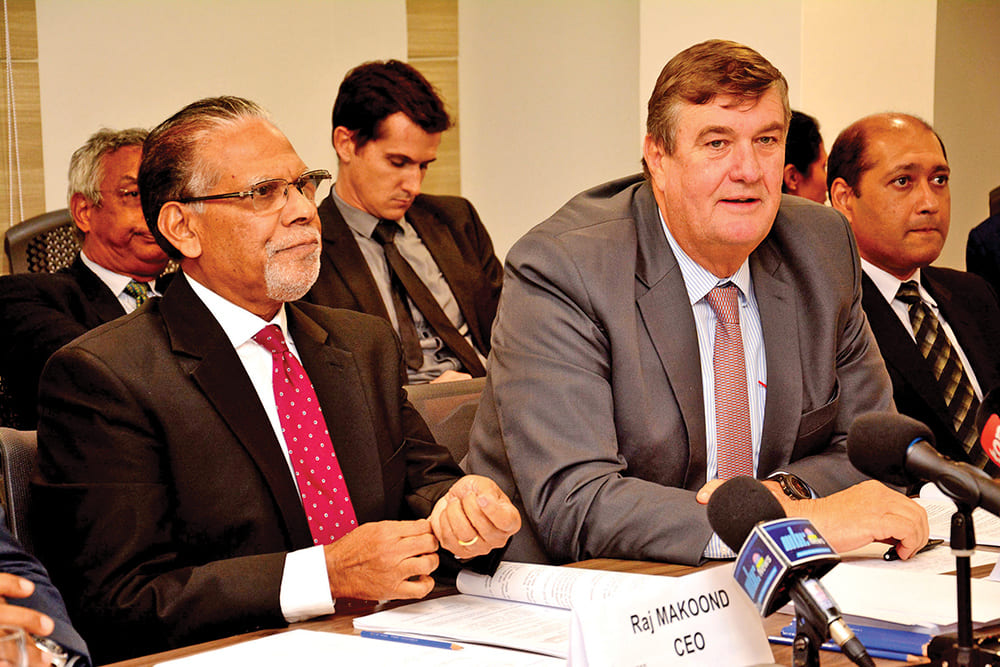
Arnaud Dalais addressing a Mauritian private-sector press briefing, seated at a table with microphones
Mauritian economic policy is negotiated through structured engagement between government and organised business. Arnaud Dalais chaired the Joint Economic Council (2000–2002) and Business Mauritius (2015–2017).

v The consultative model

How policy actually gets made here.

Mauritius operates a consultative economic model with unusually formal machinery. The Joint Economic Council, created in the 1970s, served as the coordinating body of the private sector and the recognised channel through which ministries consulted business on economic and trade matters. The Mauritius Employers’ Federation, founded in the early 1960s, handled the employer side of industrial relations.

The merger of the two into Business Mauritius consolidated economic-policy representation and employer representation into one institution. It is, in effect, the private sector organised to speak with a single voice — on budgets, on labour legislation, on trade positioning and on investment promotion.

Two features of this system are worth naming. It is small: the number of people who chair these bodies over a generation is limited, and they meet the same counterparts repeatedly. And it is durable: continuity of participants tends to produce continuity of policy, which is much of what a small jurisdiction has to offer international investors who could go elsewhere.

The corresponding risk is equally clear. A consultative system concentrated among a small number of established participants can be slow to admit new entrants, and can mistake consensus among incumbents for the national interest. That tension is not unique to Mauritius, but it is sharper in a country of this size.

vi Constraints & risks

What the model
still has to solve.

Demographic ageing

A population of 1.27 million with declining fertility and rising life expectancy faces a shrinking working-age share. For labour-intensive sectors — manufacturing, hospitality, healthcare — this is a structural cost pressure, not a cyclical one.

Regulatory dependence

A financial centre accounting for over a tenth of GDP is only as strong as its international standing. Changes to tax treaties, transparency standards or listings by international bodies affect the sector faster than any domestic policy can compensate for.

Climate exposure

A small island state carries concentrated physical risk: cyclones, coastal erosion, coral degradation and water stress. Tourism, agriculture and property — three of six CIEL clusters — are directly exposed. This is why water use appears as a bond covenant rather than a footnote.

Scale and connectivity

Air and sea connectivity determine both tourism volumes and export logistics, and a small market has limited leverage over carriers. Growth in arrivals is constrained less by demand than by available seats.

Concentration of capital

A handful of diversified groups account for a substantial share of listed market activity. That concentrates both capability and risk, and makes the governance of those groups a matter of national economic consequence.

Investment momentum

The 2025 growth moderation was attributed largely to the completion of major infrastructure projects and a slowdown in new investment — a reminder that public capital expenditure has been doing significant work in headline growth figures.

vii Statistical sources

Where these figures come from

  1. World Bank — Macro Poverty Outlook and country data for Mauritius: growth estimates for 2024 and 2025, income classification, and the 2020–2021 high-income episode.
  2. Statistics Mauritius — population, employment and tourism series.
  3. International Monetary Fund — Article IV country reporting for Mauritius, 2025: unemployment and inflation figures.
  4. United States Department of State — 2025 Investment Climate Statement, Mauritius: financial-services share of GDP.
  5. CIEL Limited — corporate disclosures on operating markets and revenue currency mix.

Statistics are reproduced as published and carry the revision practices of their issuing bodies. Figures described as estimated or projected are labelled as such. Where sources differ on a value, the more conservative figure has been used.